
The world at a glance
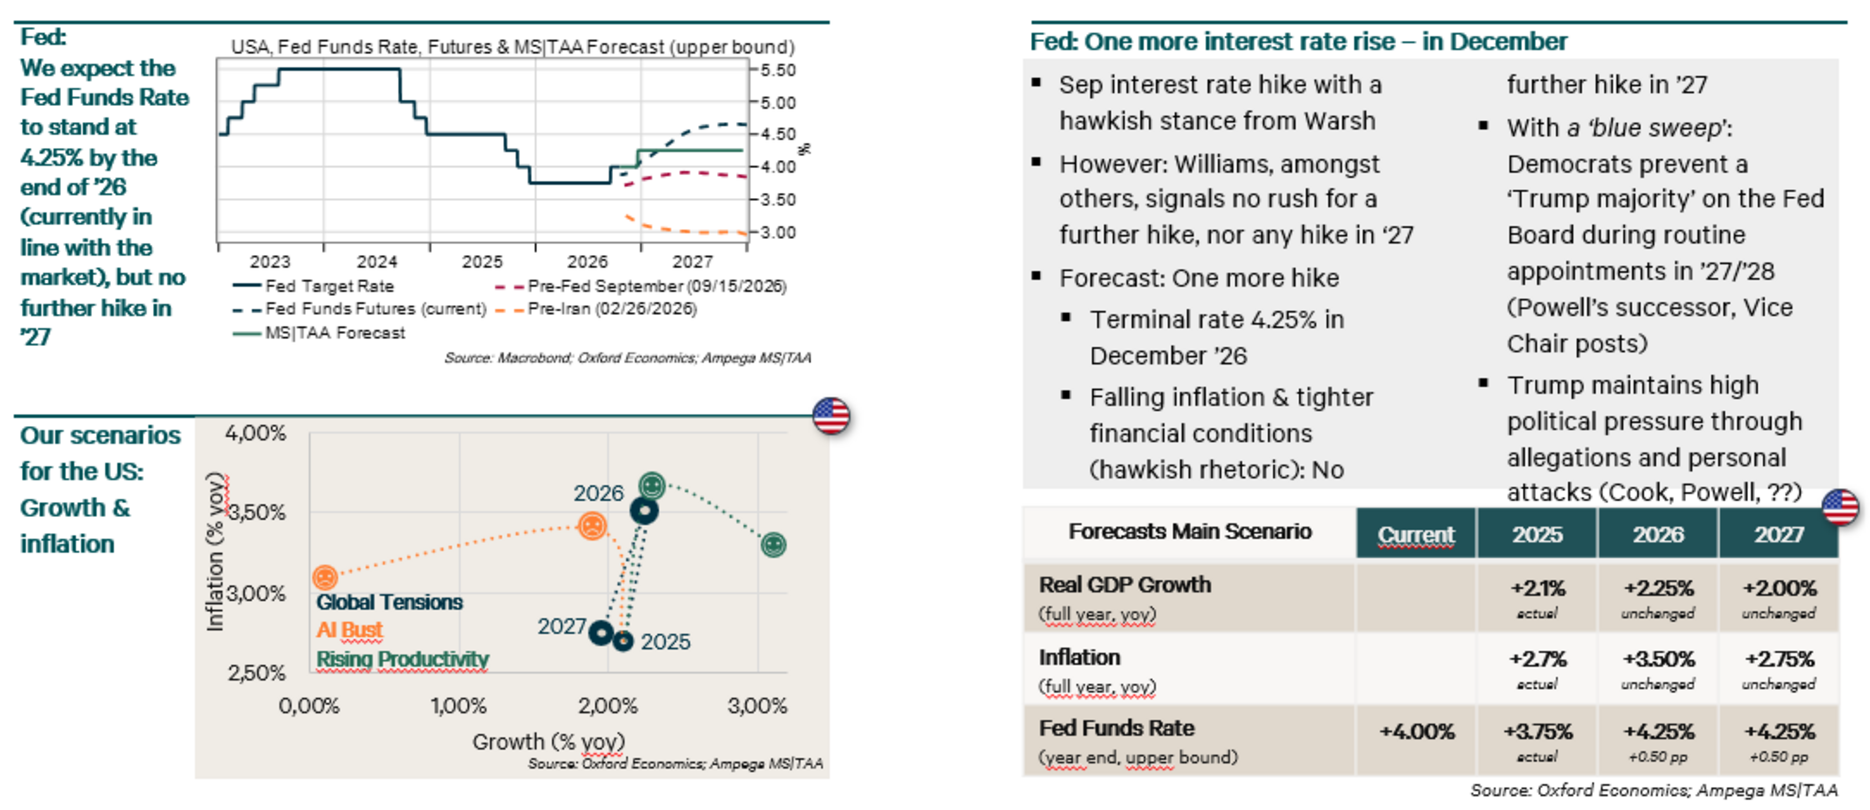
- The Fed raises its interest rate to 4,00%, marking the first rate hike since 2023, and sends a hawkish signal
- The House of Representatives passes new sanctions against Russia and its trading partners – Trump and Putin agree on a temporary easing of diesel sanctions
- G7 agree to release strategic diesel reserves
- Greenland, Denmark and the US sign an agreement on sovereignty, self-determination and the US military presence on the island
- State visit to the US: Xi and Trump pledge friendship and cooperation
- Trump invites Putin to the G20 summit in Miami
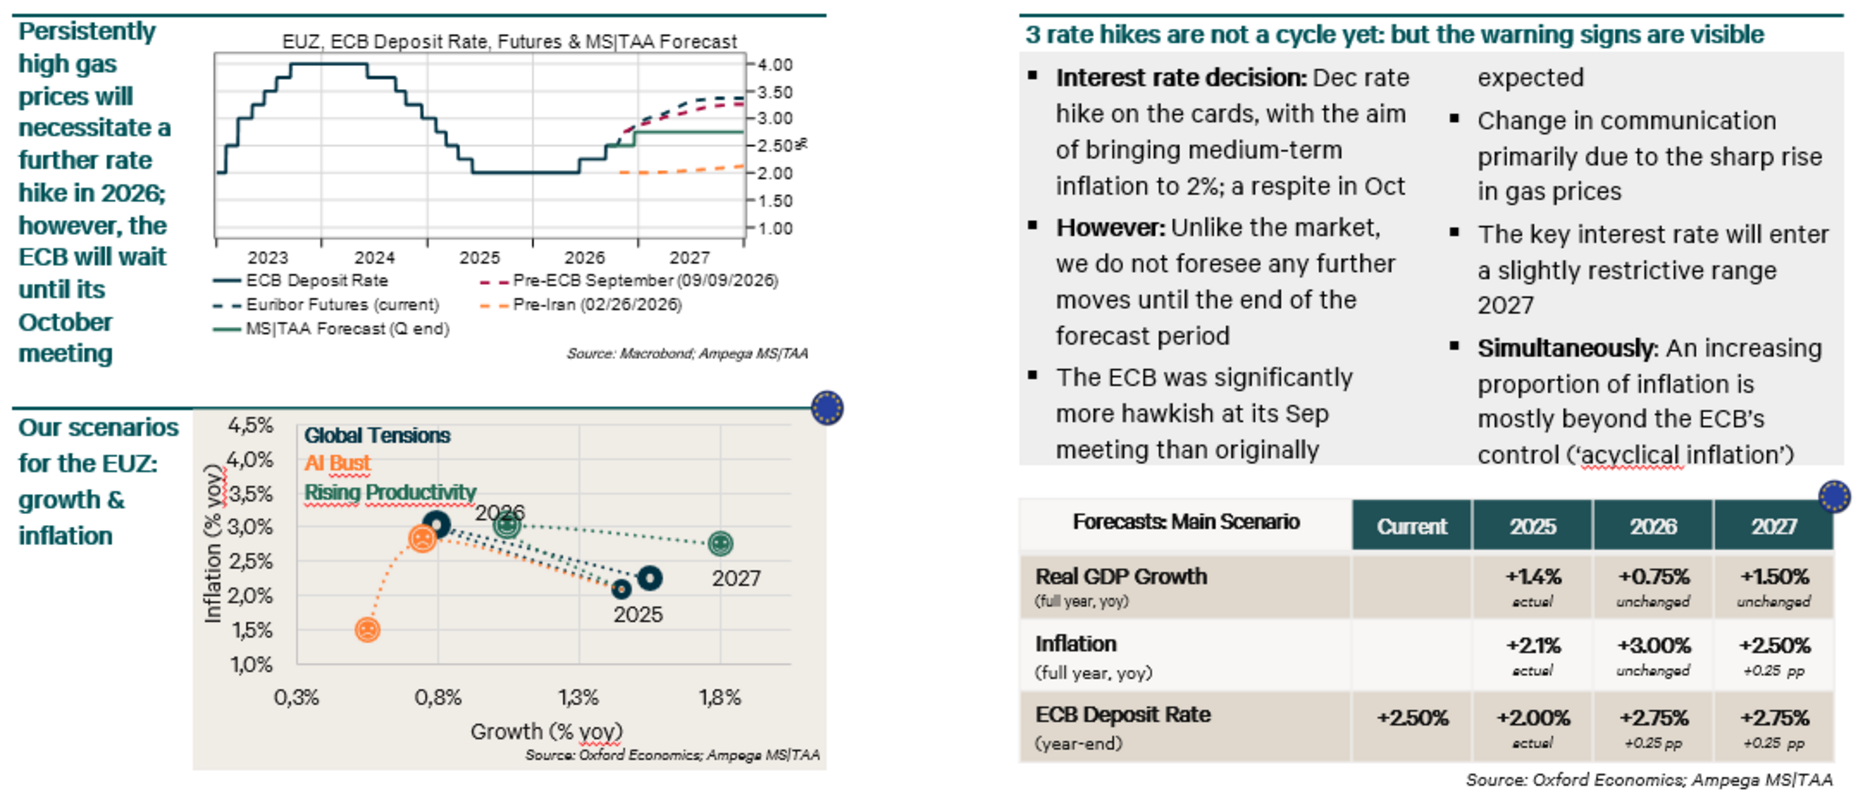
- ECB raises key interest rate to 2.50%
- Canada signals openness to becoming an ‘associated member’ of the EU
- EU and the Philippines reach agreement on a free trade deal
- According to the EU’s Copernicus Climate Service: Hottest summer in Western Europe since records began
- China agrees to limit exports of hybrid cars to the EU
- State elections:
- AfD wins by a wide margin in Saxony-Anhalt
- In Mecklenburg-West Pomerania, the AfD becomes the stronges party with nearly 40%, the CDU fails to clear the 5% threshold
- In Berlin, Die Linke becomes the largest party with almost 26%
- Leading economic institutes and the government raise their growth forecast for Germany to 1.3%
- The UAE plans to invest €40bn in Germany
- The US proposes a $10bn fund for alternative export routes to SvH
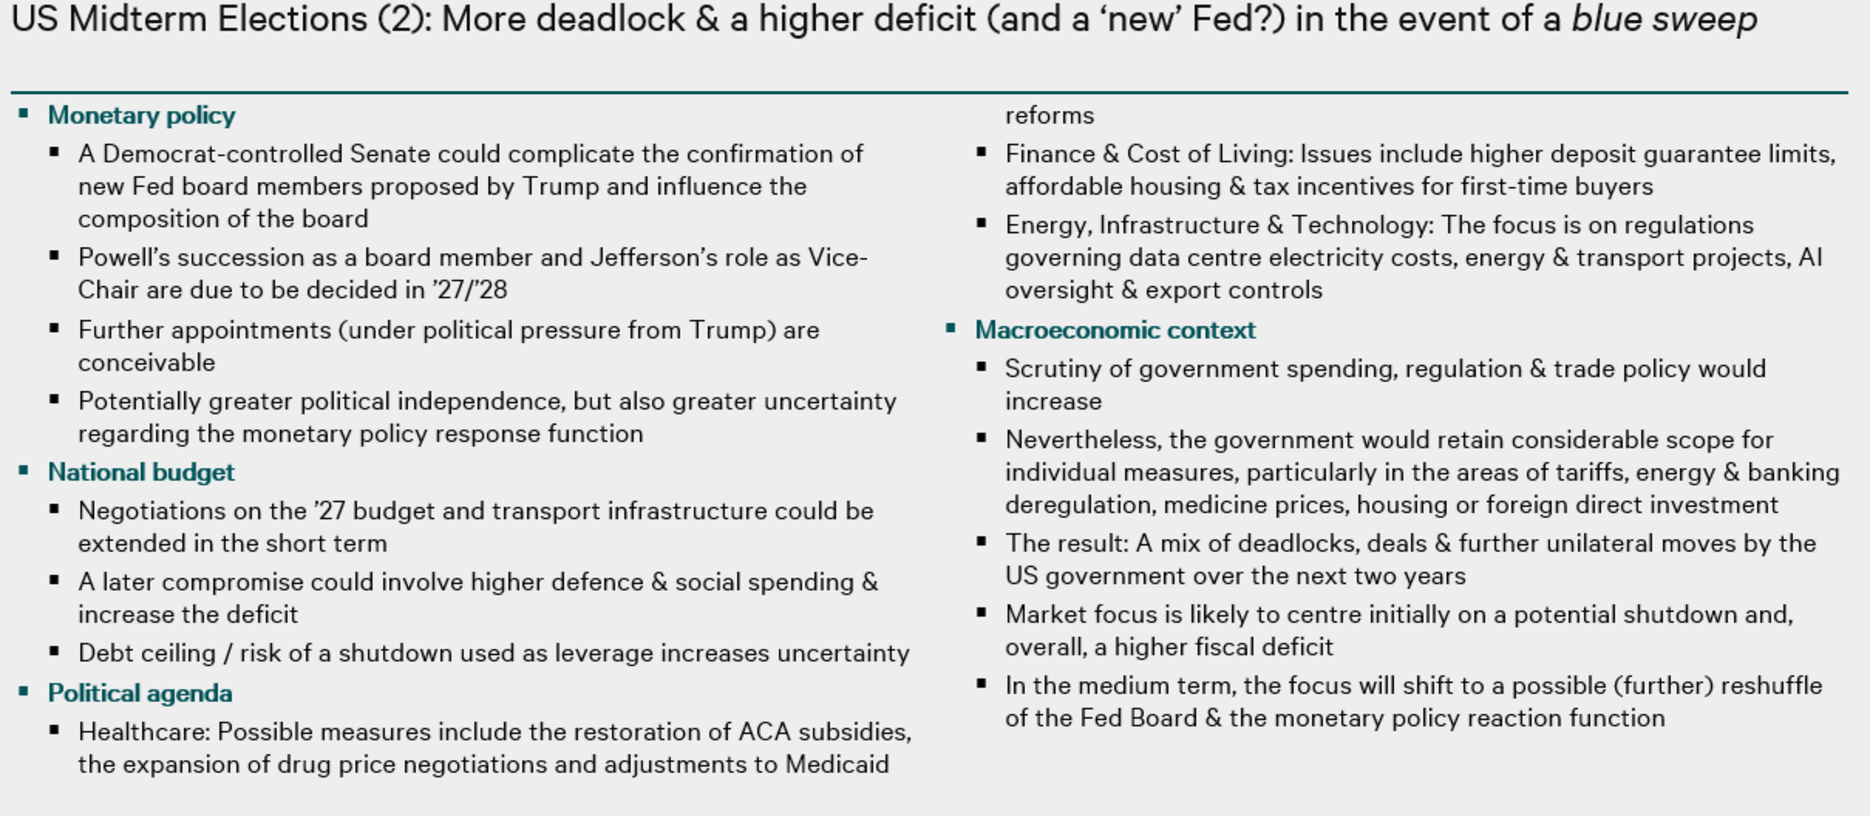
- Trump rules out US attacks on Iran ahead of the mid-term elections
- Following attacks by Houthi rebels on Saudi airports, the Saudi government launches retaliatory actions against them
- Saudi Arabia restores the East-West pipeline following Houthi attacks
- Houthis capture the port city of Mokha
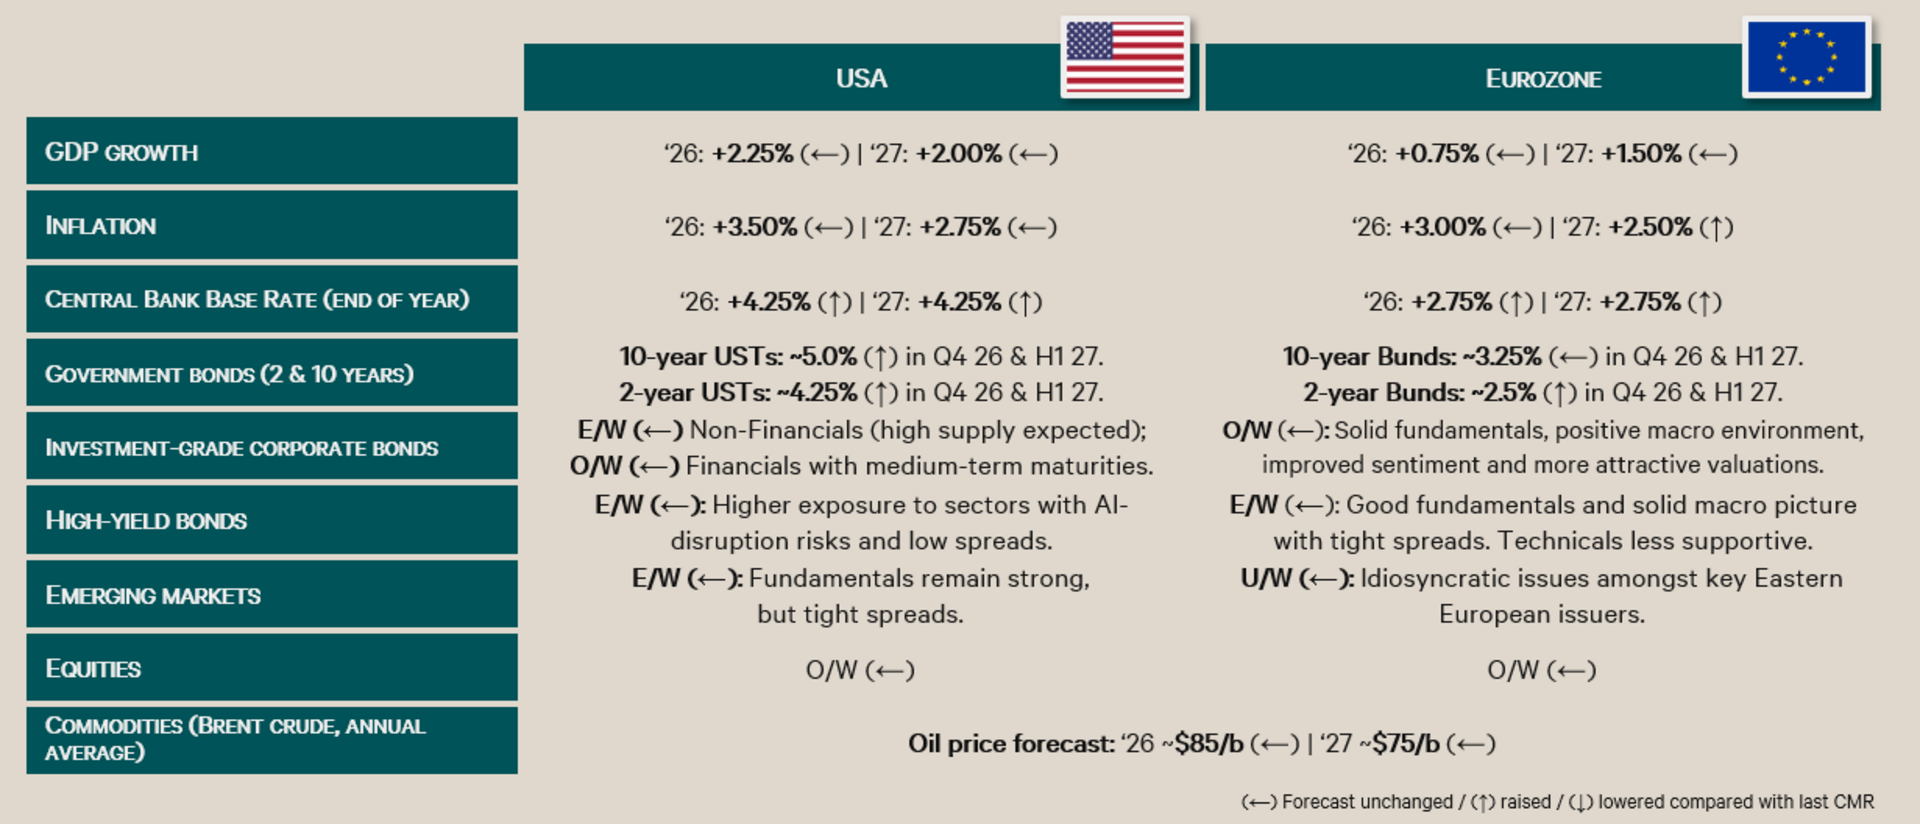
Ampega Forecast Overview Main Scenario "Global Tensions"
Market Update

Bond markets
- Bond markets experience a pitch-black month: inflation risks (high energy prices), fiscal concerns and persistently high demand for capital drive yields to multi-decade highs
- In the US, markets initially came under pressure following the Fed’s first rate hike since ’23 and hawkish comments, although part of the move was later priced out
- Europe: OAT-Bund spread at its highest level since the sovereign debt crisis due to fiscal and political concerns
- 30yr Gilts temporarily >6%
- Bolsonaro’s unexpectedly strong first-round victory provides a boost to Brazilian bonds

Equity Markets
- Rising yields and high oil prices are also weighing on sentiment in global equity markets – extending rotation out of real estate and small-caps
- In the US, the AI rally continues, although temporary cautionary reports are weighing on the market – the S&P 500 and Nasdaq hit new all-time highs
- Europe weaker amid a lack of AI equities and political concerns
- Sell-off in the semiconductor sector at the month-end: the KOSPI is particularly affected
- Mirroring the bond market, the Bovespa also benefits from election results
Macroeconomic Outlook
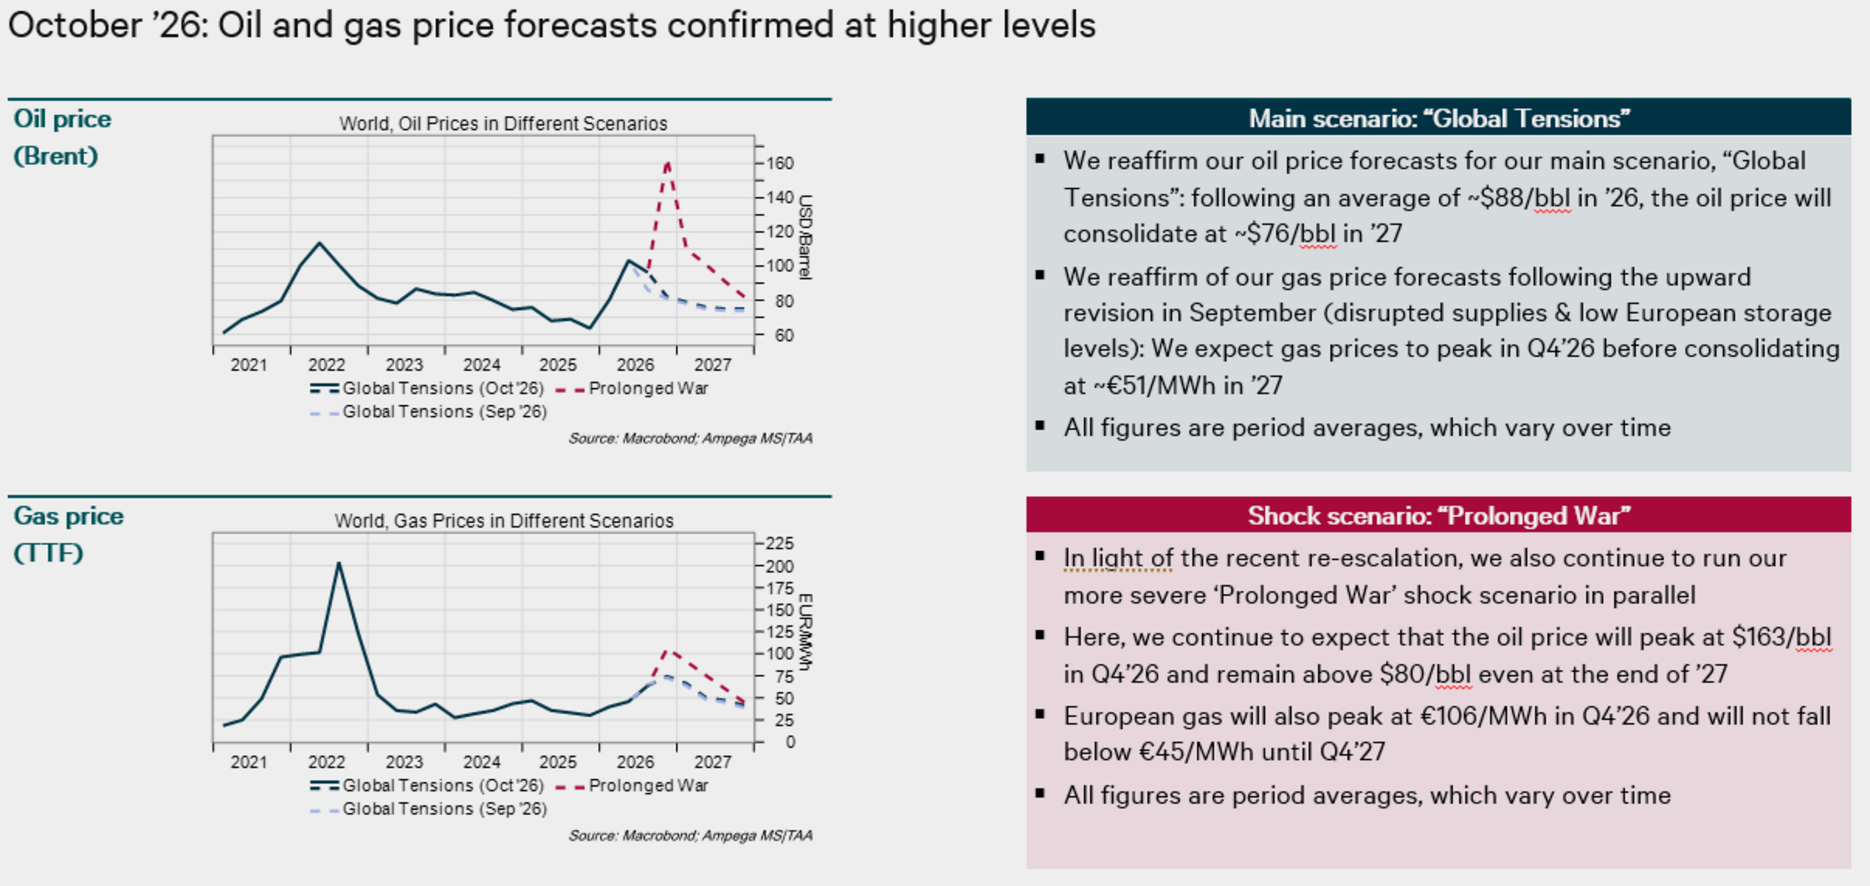
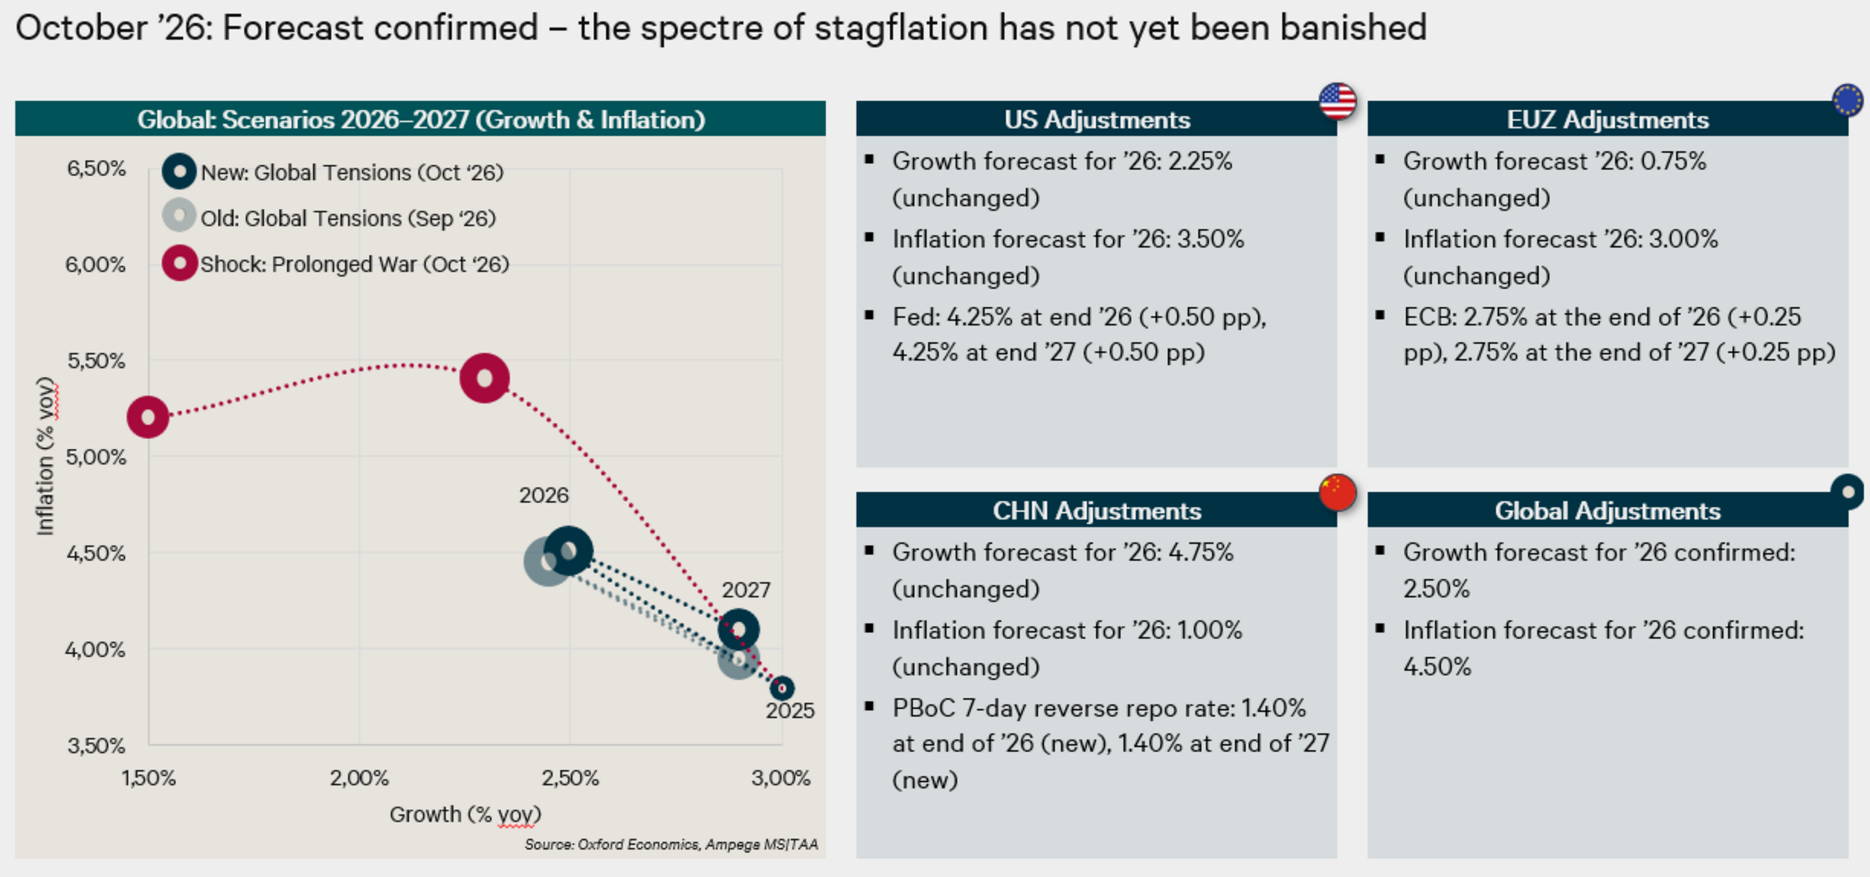
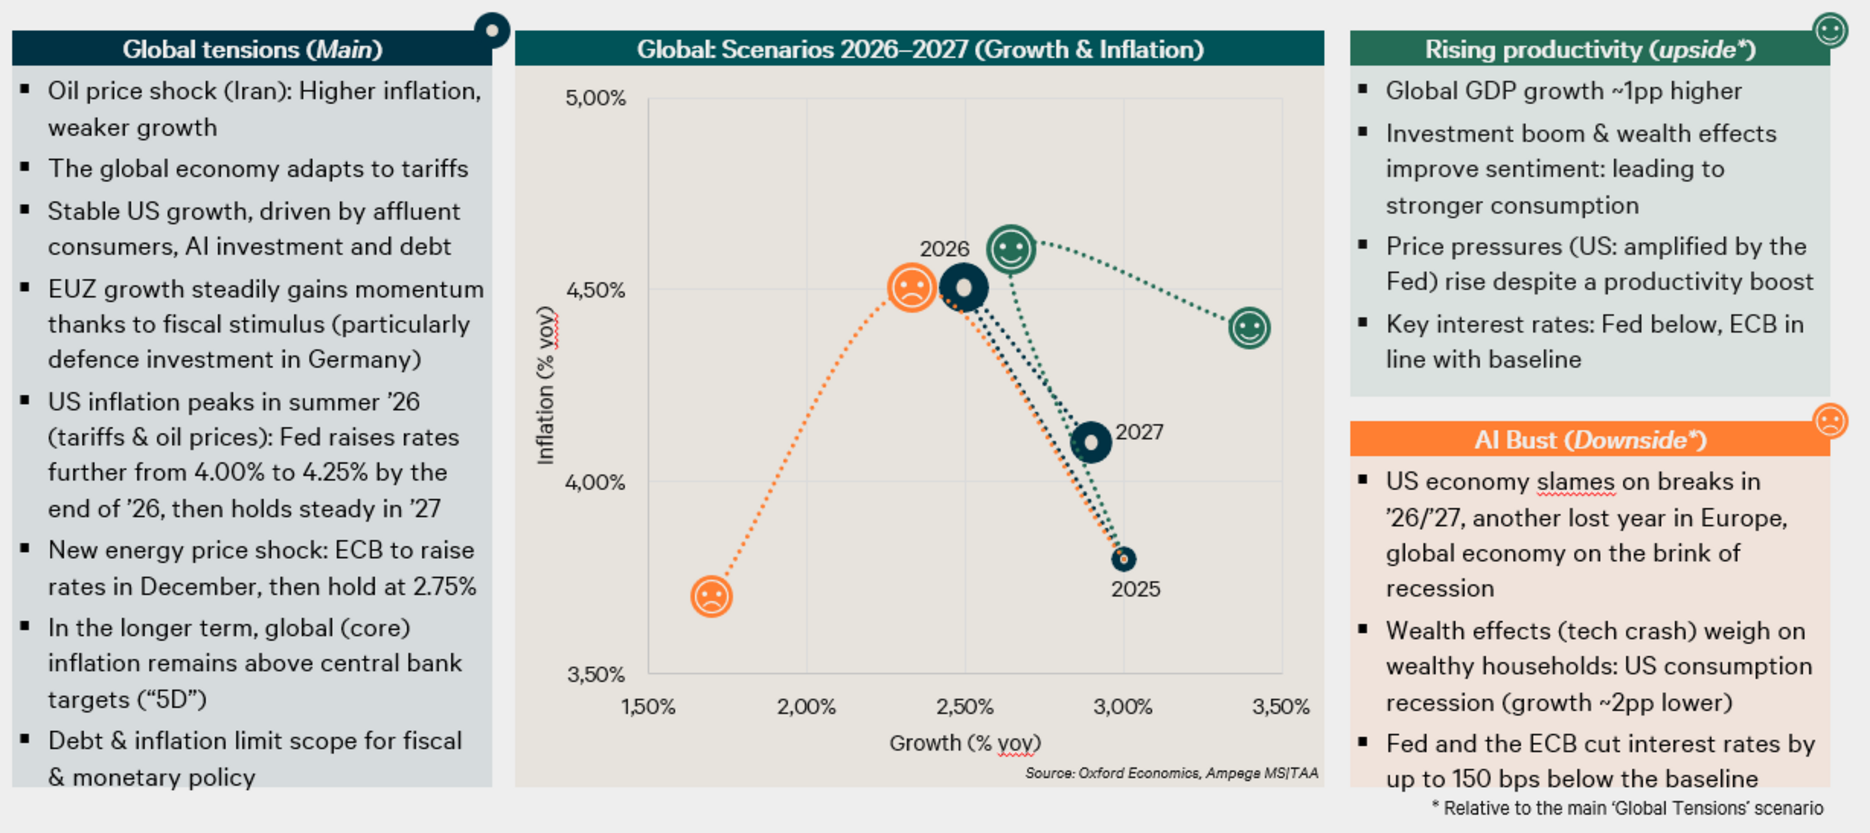
Charts of the Month | September 2026
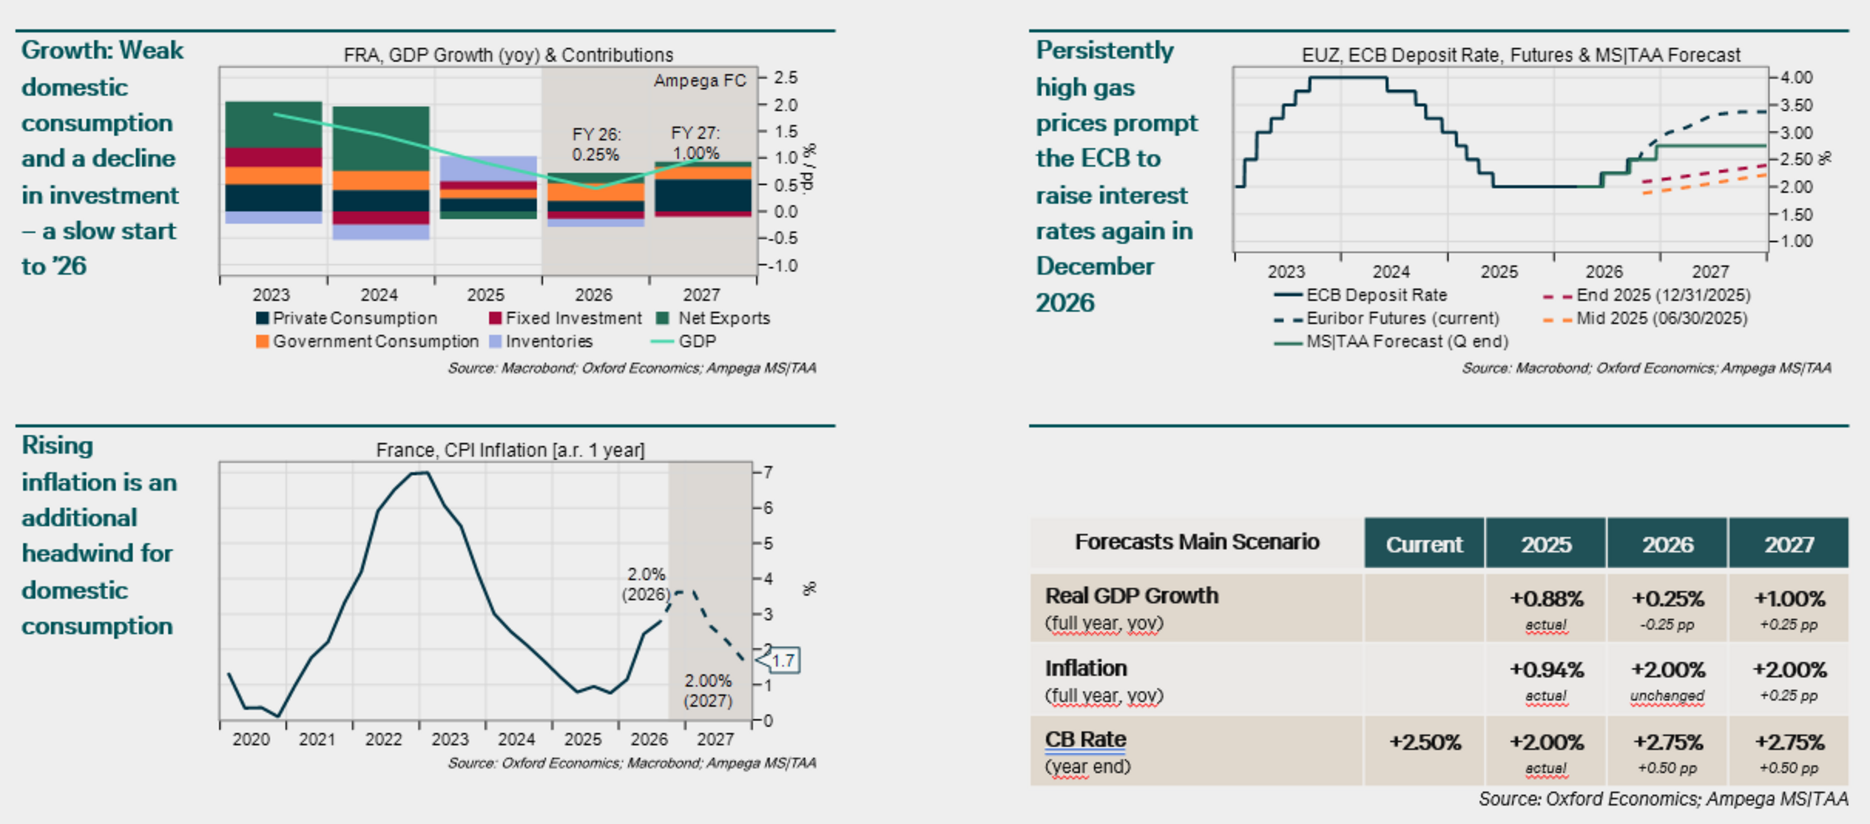
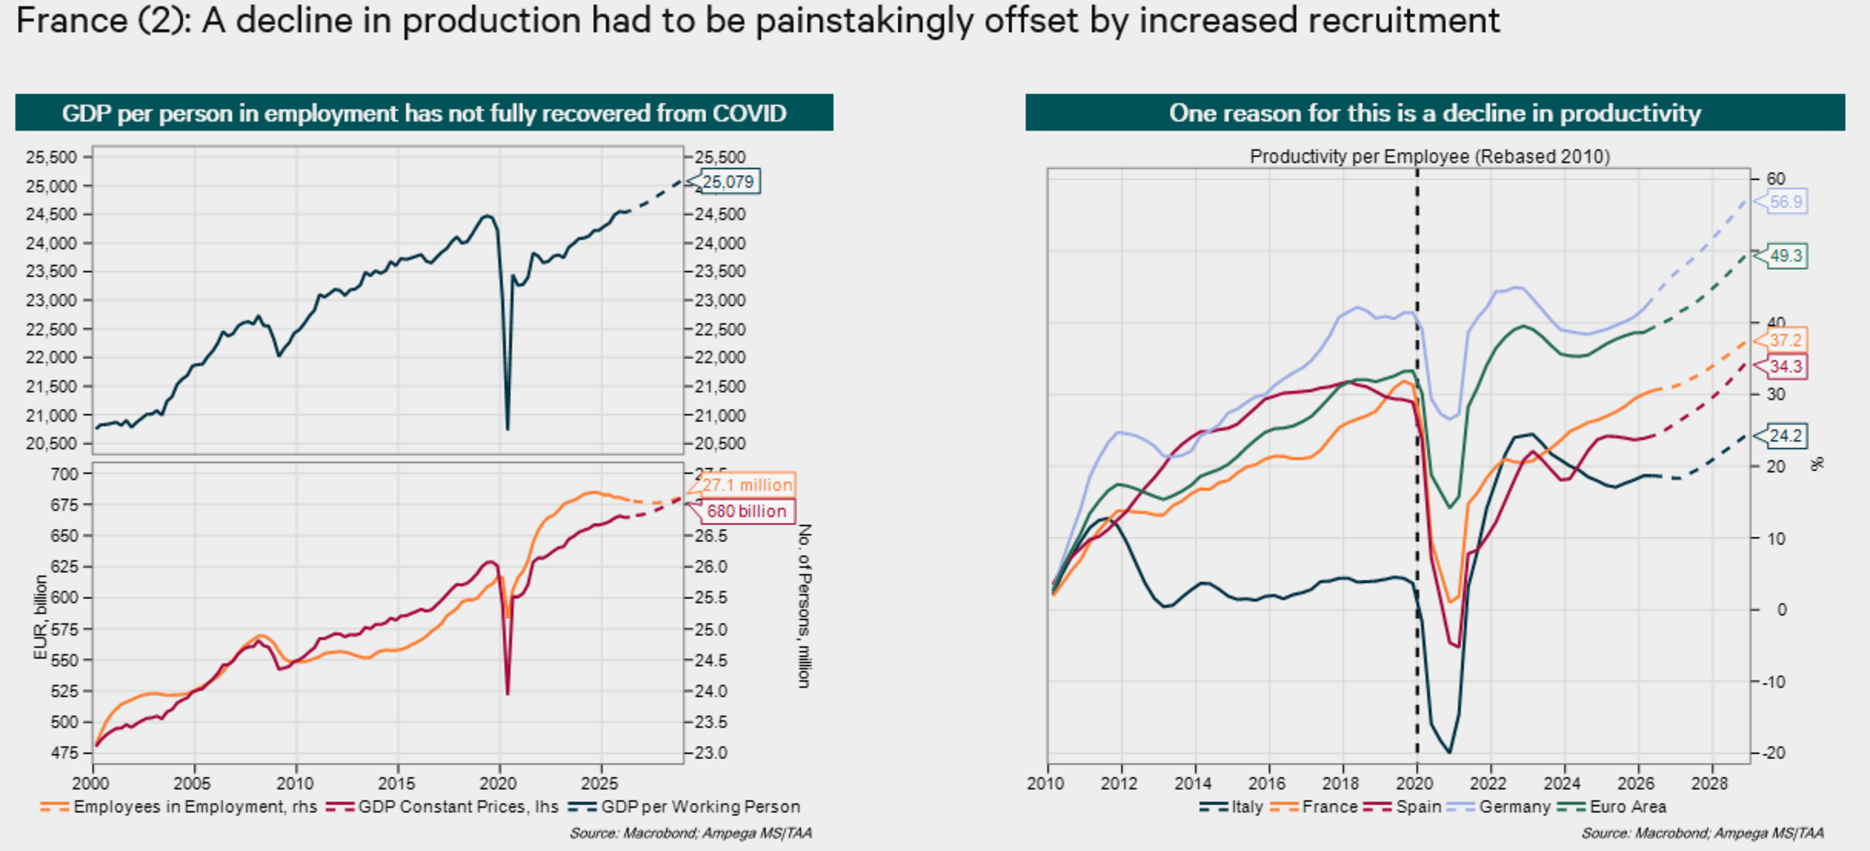
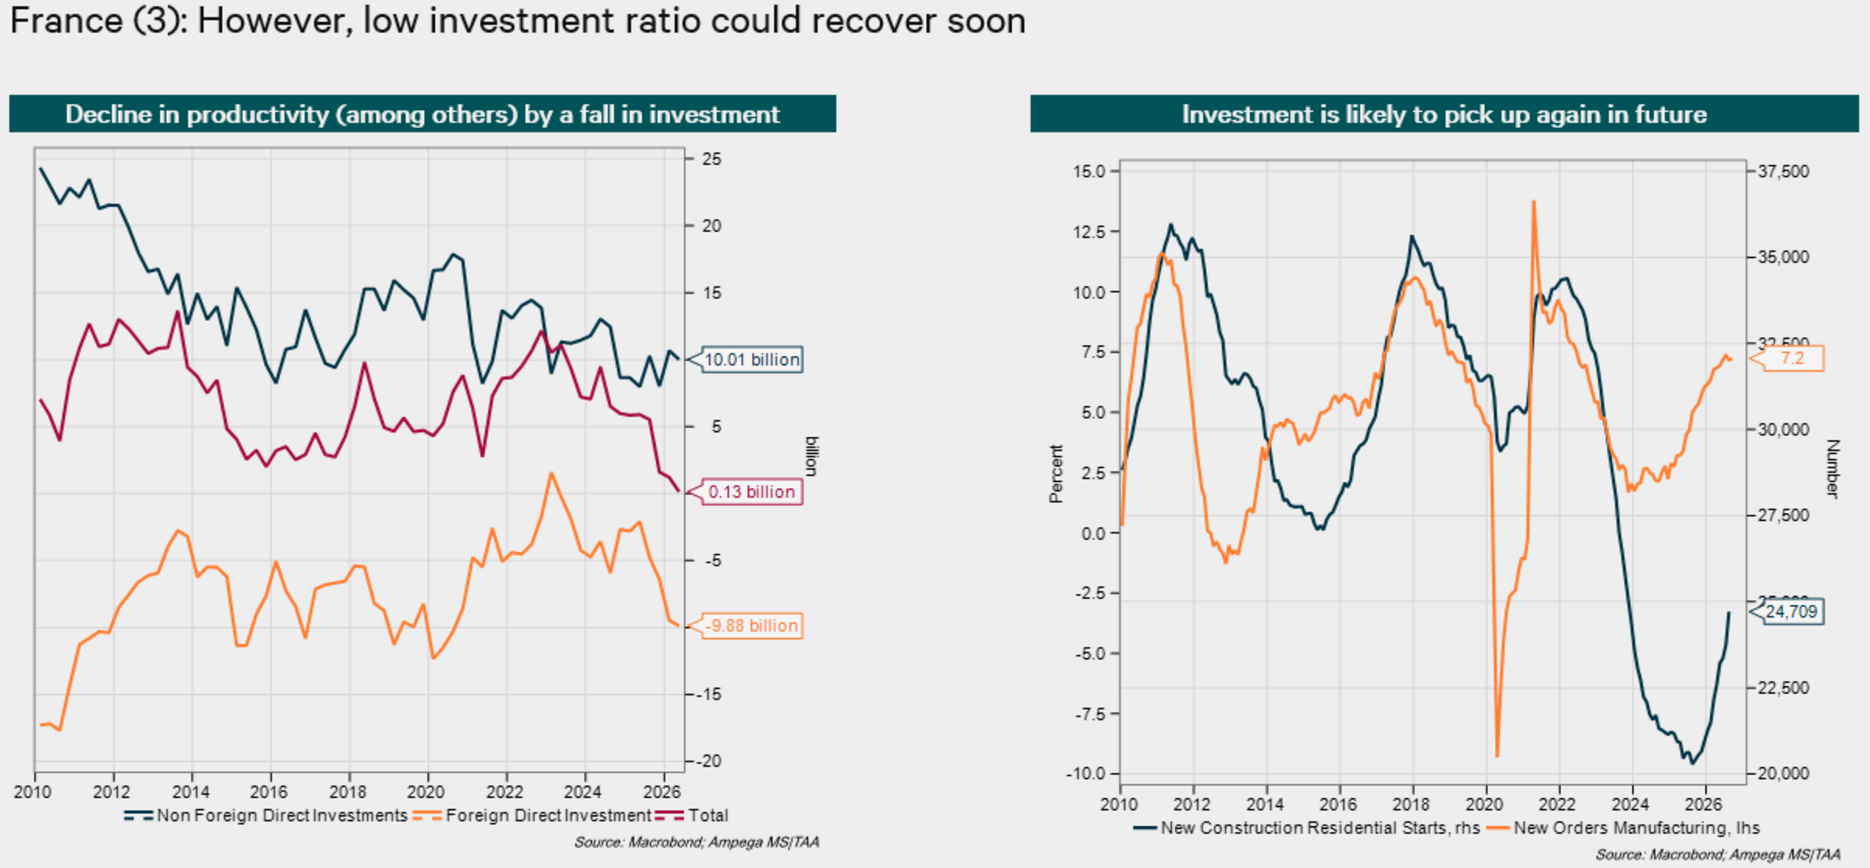
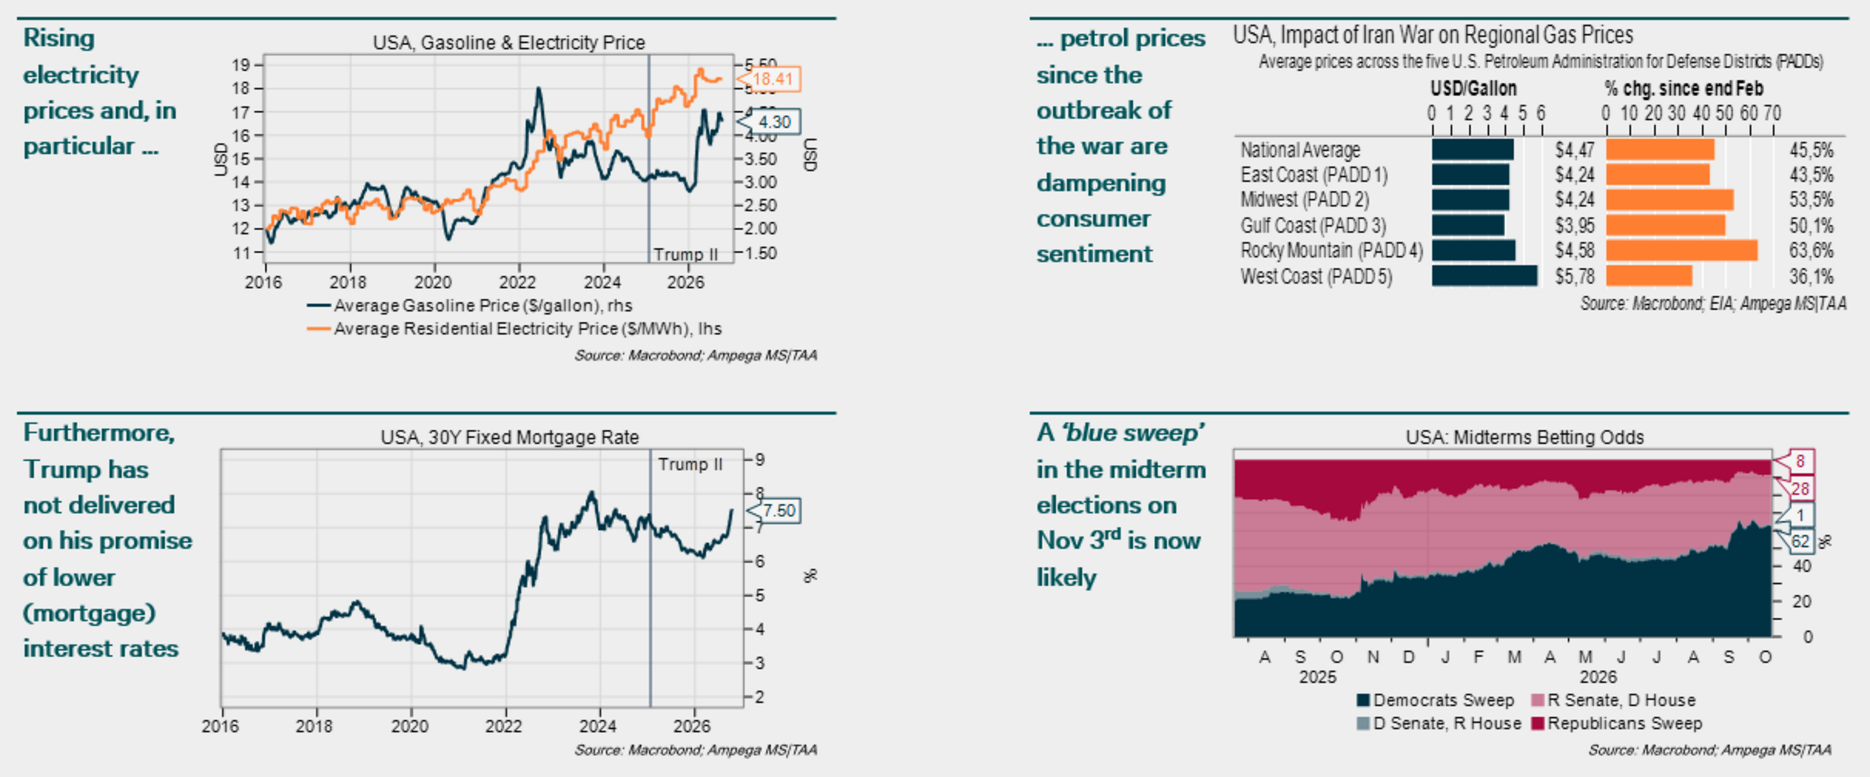
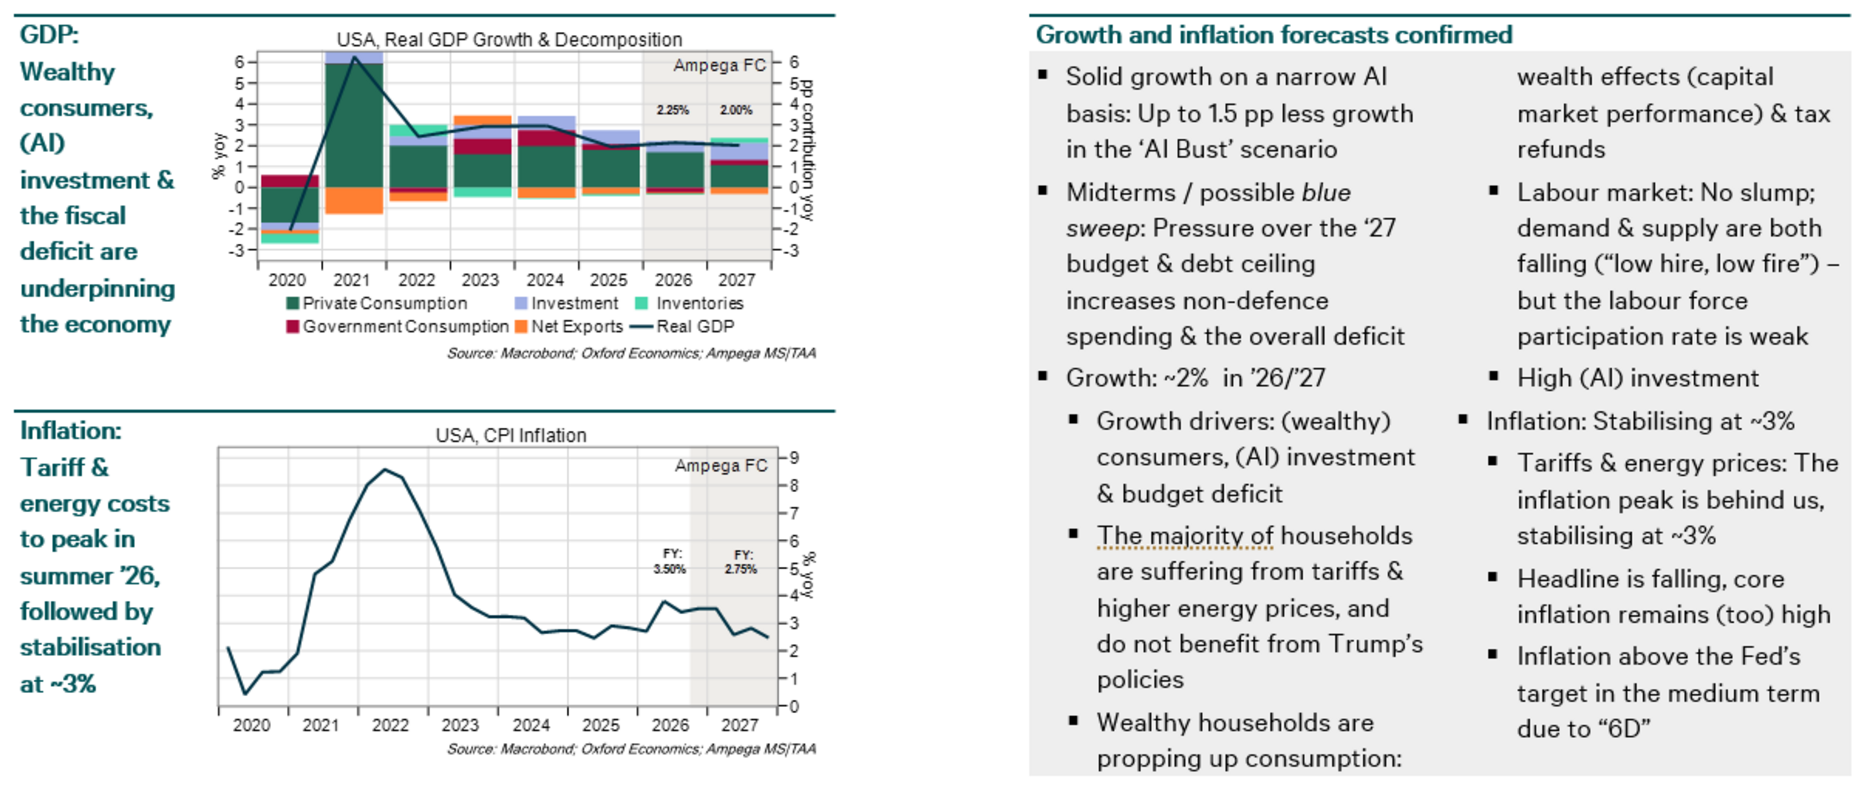
USA
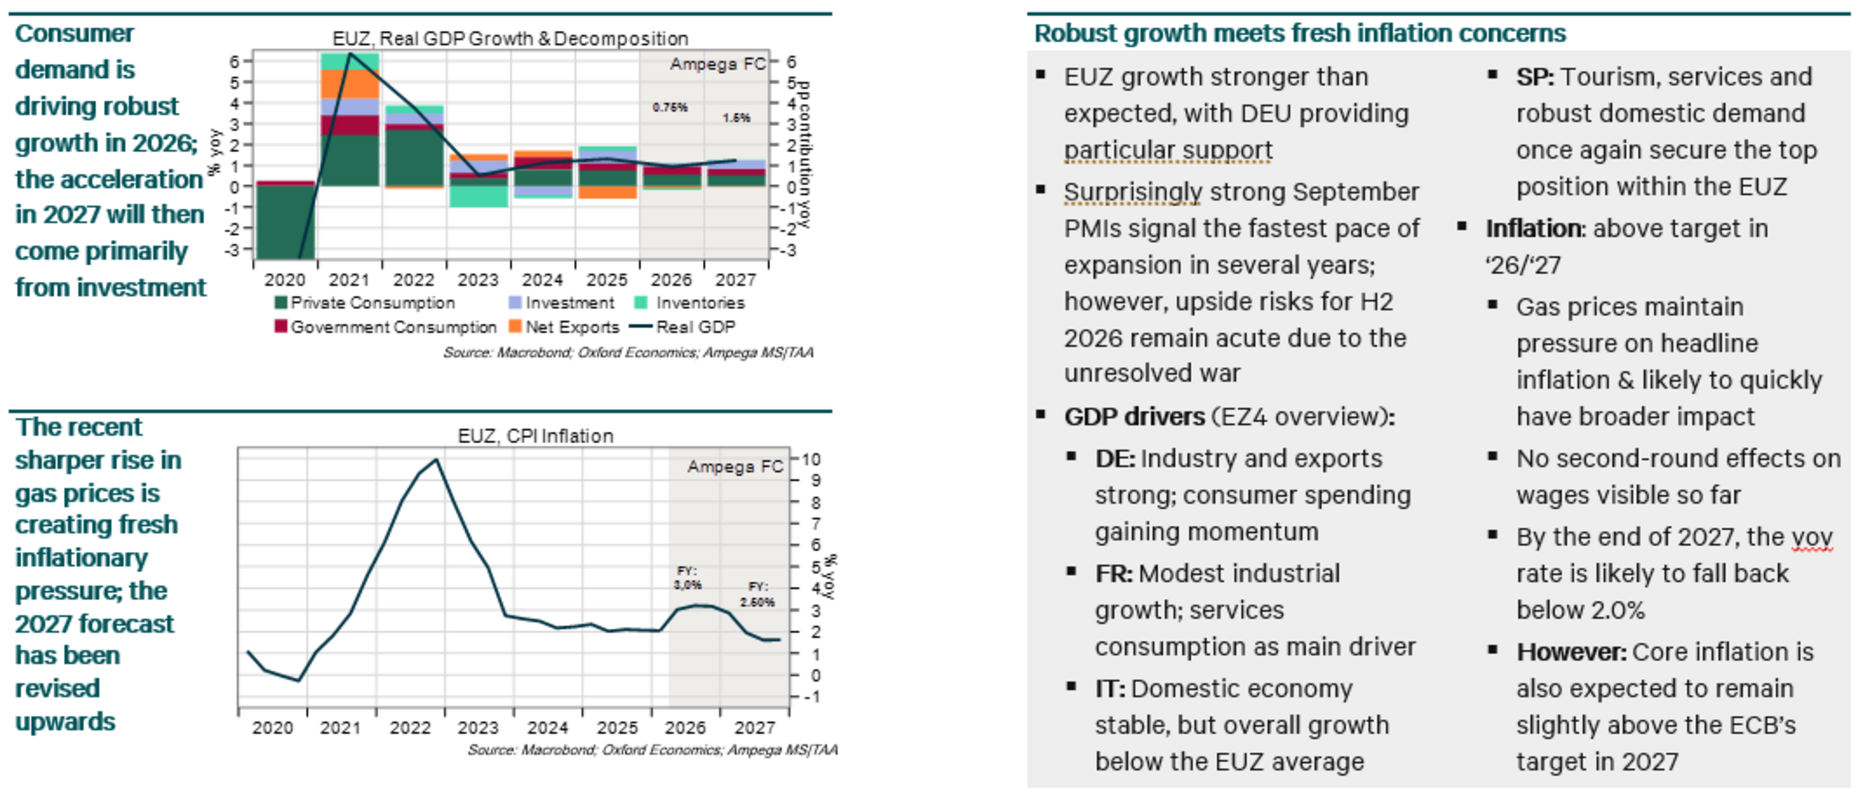
Eurozone
Disclaimer: The opinions and forecasts contained in this document are solely those of Talanx. The information and opinions are date-specific and may change at any time without prior notice. Talanx has prepared the content of this document on the basis of publicly available sources deemed to be reliable, but has not independently verified them. Consequently, no express warranty is given, nor is any such warranty implied, as to the balance, accuracy, completeness or correctness of the information or opinions contained in this document. Talanx accepts no responsibility or liability for any loss arising from the use of this document or the information contained therein, or otherwise in connection therewith. An investment decision should be made on the basis of a duly approved prospectus or information memorandum and under no circumstances on the basis of this document. This document does not constitute an offer or an invitation to subscribe for or purchase any security, nor does this document or the information contained herein form the basis of any contractual or other obligation of any kind. The financial instruments covered by this document are not suitable for every investor. Investors must make their own investment decision based on their risk profile, experience, return expectations, etc., and seek advice where appropriate. This document does not constitute investment advice. Prices and the availability of financial instruments may also change at any time. Where financial instruments are quoted in foreign currencies, exchange rate risk must be taken into account; exchange rates may affect the price or value of a financial instrument. This document is provided for your information only. This document is subject to Talanx’s copyright; it may not be reproduced in whole or in part, nor may it be redistributed to any other person. Any quotations from this document must be accompanied by a reference to the source. Any use beyond this requires the prior written consent of Talanx.